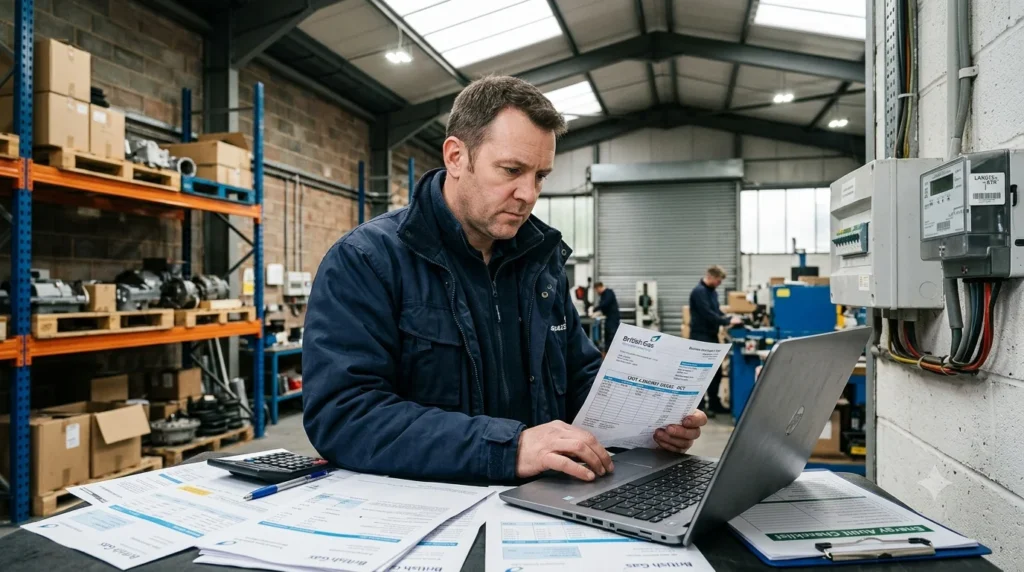
Electricity is a significant operating expense for many UK businesses. Offices, shops, restaurants, warehouses and manufacturing sites all consume energy differently, making it important to understand how each bill is calculated.
A business can estimate its electricity costs by multiplying the electricity used in kilowatt-hours by its unit rate, then adding standing charges, taxes and any additional supplier fees.
Regular monitoring makes it easier to identify waste, prepare accurate budgets and compare commercial energy contracts.
What Is the Formula for Calculating Business Electricity Costs?
The basic calculation is:
Electricity cost = Energy consumption in kWh × Unit rate
However, this only calculates the usage element of the bill. A more complete formula is:
Total bill = Usage charge + Standing charge + Additional charges + VAT
When a unit rate or standing charge is shown in pence, it must be divided by 100 to convert it into pounds.
For example, if a business uses 5,000 kWh and pays 24 pence per kWh:
5,000 × £0.24 = £1,200
The business must then add the standing charge, applicable levies, supplier fees and VAT to estimate the final amount payable.
Which Information Is Needed for the Calculation?
Most of the required information can be found on a recent business electricity bill.
| Information | Where to Find It | Why It Matters |
| Electricity consumption | Meter reading or bill | Shows the number of kWh used |
| Unit rate | Tariff details | Determines the cost of each kWh |
| Standing charge | Tariff details | Daily fixed charge for the supply |
| Billing period | Bill summary | Establishes how many days to include |
| Additional charges | Bill breakdown | May include network or capacity costs |
| VAT rate | Tax summary | Determines the final tax amount |
| Meter type | Account details | Affects how consumption is measured |
Businesses comparing small business energy deals should check all these elements. A low unit rate does not always produce the cheapest total bill when standing charges and additional costs are included.
How Can a Business Read Its Electricity Consumption?
Electricity consumption is measured in kilowatt-hours, usually written as kWh. One kilowatt-hour represents the energy used by a 1,000-watt appliance running for one hour.
A business should compare the opening and closing meter readings for the relevant billing period:
Closing meter reading − Opening meter reading = Electricity consumed
If the opening reading was 48,200 and the closing reading was 53,200, the business used:
53,200 − 48,200 = 5,000 kWh
Actual readings provide a more reliable calculation than estimated readings. Estimated bills may be too high or too low, particularly where the business has seasonal activity or recently changed its equipment.
Smart meters and half-hourly meters can provide more detailed consumption information. Half-hourly data is particularly useful because it reveals when the business uses the most electricity rather than simply showing the monthly total.
How Is the Unit Rate Applied?
The unit rate is the price paid for each kilowatt-hour of electricity. It is usually displayed in pence per kWh.
If the rate is 26.5p per kWh and the business uses 8,000 kWh:
8,000 × 26.5p = 212,000p
After converting pence into pounds:
212,000 ÷ 100 = £2,120
Some commercial contracts have different unit rates depending on the time of day. A business may pay separate daytime, evening, night or weekend rates. Each consumption period must therefore be calculated separately before the totals are added together.
How Is the Standing Charge Calculated?
The standing charge is a fixed daily amount payable regardless of how much electricity the business consumes. It contributes towards maintaining the electricity connection, meter and supply network.
The formula is:
Daily standing charge × Number of billing days
For example, a standing charge of 80p per day over a 30-day billing period would cost:
£0.80 × 30 = £24
Standing charges deserve particular attention when reviewing business utility options. They can have a greater effect on small premises with relatively low consumption because the fixed fee represents a larger proportion of the total bill.
What Does a Complete Business Electricity Calculation Look Like?
Consider a business that uses 12,000 kWh during a 30-day billing period. Its contract includes a unit rate of 24.5p per kWh and a daily standing charge of 85p.
| Bill Element | Calculation | Cost |
| Electricity usage | 12,000 × £0.245 | £2,940.00 |
| Standing charge | 30 × £0.85 | £25.50 |
| Other bill charges | Supplier calculation | £160.00 |
| Subtotal before VAT | £2,940 + £25.50 + £160 | £3,125.50 |
| VAT at 20% | £3,125.50 × 20% | £625.10 |
| Estimated total | £3,125.50 + £625.10 | £3,750.60 |
The additional £160 in this example is illustrative. The actual figure could include the Climate Change Levy, network-related costs, meter charges or other contract-specific items.
Which Additional Charges Can Appear on the Bill?
Commercial electricity bills are often more complicated than domestic bills. Depending on the supplier, meter and contract, a business may encounter:
- Climate Change Levy
- Metering charges
- Network and distribution costs
- Capacity or availability charges
- Reactive power charges
- Renewable energy-related costs
- Late payment or administration fees
Some contracts include certain costs within the unit rate, while others show them separately as pass-through charges. The business should check the tariff agreement rather than assuming that the advertised unit rate represents the complete electricity cost.
How Does VAT Affect Business Electricity Costs?
Most business electricity is charged at the standard rate of VAT. However, a reduced rate may apply when electricity use falls within the de minimis threshold or where qualifying charitable and non-business activities are involved.
Electricity may be treated as de minimis when average consumption does not exceed 33 kWh per day or 1,000 kWh per month. Eligibility depends on the circumstances, so the business should confirm the VAT treatment shown by its supplier.
A VAT-registered business may normally be able to reclaim eligible VAT on electricity used for taxable business activities. Records should be retained and entered correctly in the company’s accounts. Using free accounting software can make it easier to categorise bills and monitor energy spending.
How Can Equipment-Level Electricity Costs Be Calculated?
Businesses can identify expensive equipment by calculating the cost of running each appliance, machine or system.
The formula is:
Power in watts ÷ 1,000 × Operating hours × Unit rate
Suppose a 2,000-watt commercial heater operates for six hours a day on 22 working days each month:
2,000 ÷ 1,000 = 2 kW
2 kW × 6 hours × 22 days = 264 kWh
At a unit rate of 25p per kWh:
264 × £0.25 = £66 per month
If the business operates five identical heaters under the same conditions, the estimated monthly usage cost would be £330 before standing charges and taxes.
This calculation can be repeated for lighting, computers, kitchen equipment, refrigeration, air conditioning, production machinery and electric vehicle chargers.
How Can Annual Electricity Costs Be Forecast?
A simple annual forecast can be produced by multiplying average monthly consumption by 12. However, this may be inaccurate for seasonal businesses.
A better approach is to review at least 12 months of bills and separate consumption into relevant periods. For example, a restaurant may consume more energy during the winter, while an air-conditioned office may experience its highest usage during the summer.
The forecast should include:
- Expected monthly consumption
- Current contractual unit rates
- Standing charges for the full period
- Known supplier or network charges
- Applicable VAT
- A reasonable allowance for changes in activity
Electricity forecasts can then be incorporated into the company’s management accounts. This allows decision-makers to see whether energy costs are rising faster than revenue or reducing the company’s operating margin.
How Can Cost Per Product or Service Be Calculated?
A business may also need to allocate electricity costs to individual products, customers, departments or locations.
If a workshop’s monthly electricity bill is £4,000 and it manufactures 2,000 units, the average electricity cost per unit is:
£4,000 ÷ 2,000 = £2 per unit
This provides a useful starting point, but it may not reflect the actual energy consumed by different products. A more accurate approach is to measure the operating time and power demand of each production process.
Service businesses can calculate electricity cost per employee, workstation, appointment or opening hour. These measurements help the business set prices and identify which parts of the operation are least efficient.
How Can a Business Improve the Accuracy of Its Calculations?
The most efficient calculation system combines actual meter data with a consistent monthly review process. Bills should be checked against meter readings rather than automatically approved for payment.
Businesses should also:
- Record readings on the same day each month
- Separate fixed charges from consumption costs
- Compare estimated readings with actual readings
- Investigate unexpected changes immediately
- Track costs by location or department
- Record contract renewal dates
- Compare usage with business activity levels
A sudden increase does not always mean the unit rate has changed. It could be caused by faulty equipment, longer operating hours, heating controls, refrigeration problems or appliances being left on overnight.
How Can Electricity Costs Be Reduced?
Once the business understands where the money is being spent, it can prioritise changes that offer measurable savings.
Low-cost actions include switching off unused equipment, adjusting heating schedules, preventing unnecessary standby consumption and checking that timers match opening hours.
Larger improvements may include LED lighting, better insulation, efficient refrigeration, upgraded machinery or smart energy controls.
An energy audit can identify the equipment and working practices responsible for the highest consumption. Businesses can then focus on actions with a reasonable payback period instead of replacing equipment without evidence.
The company should also review its contract before the renewal window closes. Comparing unit rates, standing charges, contract duration and pass-through costs can help reduce business electricity costs without affecting day-to-day operations.
For premises with suitable roofs and substantial daytime consumption, solar for business premises may reduce the amount of electricity purchased from the grid. The investment should be assessed using realistic generation, maintenance and payback assumptions.
What Common Calculation Mistakes Should Be Avoided?
One common mistake is comparing tariffs using only the unit rate. A contract with a slightly lower rate may still be more expensive if it includes a high standing charge or costly additional fees.
Other frequent errors include confusing watts with kilowatts, failing to convert pence into pounds, overlooking VAT, using estimated consumption and assuming equipment operates at full power continuously.
Businesses should also avoid applying a domestic tariff estimate to commercial premises. Business contracts can include different billing structures, taxes, renewal terms and demand-related charges.
How Often Should Electricity Costs Be Reviewed?
Most small businesses should review electricity consumption every month. Energy-intensive companies may benefit from weekly or daily monitoring, particularly where smart or half-hourly meter data is available.
Contract terms should be reviewed several months before their end date. Leaving the process too late may reduce the time available to obtain quotations and assess the complete cost of each offer.
A monthly comparison of consumption, total cost and cost per kWh can quickly reveal whether savings measures are working.
Conclusion
To calculate electricity costs for a business efficiently, start with actual kWh consumption, multiply it by the contracted unit rate and add standing charges, taxes and supplier-specific fees.
The calculation becomes more valuable when it is repeated regularly and compared with operating hours, production volumes or revenue.
Accurate electricity tracking helps a business budget confidently, detect unusual consumption and evaluate energy-saving investments. It also provides the evidence needed to compare tariffs properly, rather than choosing a contract based on its headline unit rate alone.
FAQs About Calculating Business Electricity Costs
How is business electricity cost per kWh calculated?
Divide the total electricity-related cost by the number of kWh used. For a clearer comparison between tariffs, calculate the usage charge separately from standing charges, VAT and other fees.
What is the difference between kW and kWh?
A kilowatt, or kW, measures power demand at a particular moment. A kilowatt-hour, or kWh, measures the amount of electricity consumed over time.
Can a business estimate electricity costs without a bill?
Yes. It can estimate consumption using the power rating and operating hours of each appliance. However, meter readings or previous bills will usually produce a more reliable forecast.
Why is the estimated bill different from the supplier’s bill?
The supplier’s total may include standing charges, taxes, network costs, meter fees and contract-specific charges that were not included in the estimate. The supplier may also have used an estimated meter reading.
Should VAT be included in an electricity budget?
Yes. Cash-flow forecasts should include the gross amount the business expects to pay. VAT-registered businesses can record any recoverable VAT separately in their accounting system.
What is the easiest way to monitor electricity spending?
Record monthly consumption, total bill value, effective cost per kWh and operating activity in a spreadsheet or accounting platform. Smart-meter data can provide more detailed monitoring.
Expert Blogger | Strategic thinker anticipating future directions for UK business