Closing A Company On Companies House: How To Do It In 2026?

UK Startup Blog Archive
Table of Contents
Closing a company on Companies House is the formal process of removing a limited company from the Companies Register so that it legally ceases to exist.
For many solvent businesses that have stopped trading and settled their affairs, voluntary strike-off is the simplest route.
However, submitting a strike-off application does not close the company immediately.
Directors must first make sure the company qualifies, settle outstanding business matters, deal with tax and employees, notify affected parties and allow time for possible objections.
The correct closure method also depends on the company’s financial position. A solvent business may be suitable for voluntary strike-off or a Members’ Voluntary Liquidation, while a company that cannot pay its debts may need a formal insolvency process instead.
Understanding each stage before starting can reduce the risk of the application being rejected, suspended or withdrawn.
When Should You Consider Closing A Company?
Closing a limited company may be appropriate when there is no longer a practical reason to keep it operating.
Common situations include:
- The Business Has Stopped Trading: The company has permanently stopped providing goods or services and the directors have no plans to restart it.
- The Company Has Never Traded: A company may have been incorporated for a business idea or project that never went ahead.
- The Business Is No Longer Viable: Falling demand, rising costs or other commercial pressures may make continuing the business unrealistic.
- The Directors Are Retiring: Directors may decide to close the business when they retire and there is nobody taking over the company.
- The Company Is No Longer Required: A group of businesses may close a subsidiary or special-purpose company that has completed its original purpose.
- The Business Cannot Pay Its Debts: Closure may be necessary, although voluntary strike-off should not be used as a substitute for a formal insolvency procedure.
Closure is not always the best option. If the business may be used again in the future, keeping the company dormant could be more suitable than dissolving it.
Which Company Closure Option Is Right For Your Situation?
There is more than one way to stop operating a UK limited company. The company’s solvency, assets, debts and future plans will determine which route is appropriate.
| Option | When It May Be Suitable | What Happens |
| Voluntary Strike-Off | A solvent company that has stopped trading and meets the strike-off conditions | The company is removed from the Companies Register |
| Dormant Company | The business is not trading now but may be required again | The company remains registered and continues to meet Companies House filing obligations |
| Members’ Voluntary Liquidation | A solvent company with assets that need to be formally distributed | A licensed insolvency practitioner winds up the company |
| Creditors’ Voluntary Liquidation | The company is insolvent and cannot pay its debts | An insolvency practitioner realises assets and deals with creditors |
For many small companies with no debts and few remaining assets, voluntary strike-off is generally the most straightforward closure route.
A company cannot normally use voluntary strike-off simply to escape unpaid creditors or insolvency problems.
Can Your Company Be Struck Off Companies House?
A limited company must meet specific conditions before its directors apply for voluntary strike-off.
The company generally must not have:
- Traded Or Sold Stock During The Previous Three Months
- Changed Its Registered Company Name During The Previous Three Months
- Been Threatened With Liquidation
- Entered Into Certain Arrangements With Creditors Such As A Company Voluntary Arrangement
The restriction on trading does not mean directors must completely abandon the company during the three-month period.
Activities required to bring the business to an orderly close can still take place.
Directors may need to settle outstanding bills, collect money owed, obtain professional advice, complete statutory requirements and deal with property or other assets.
The important distinction is that the company should not continue normal commercial trading while preparing to use voluntary strike-off.
If the company becomes insolvent or no longer satisfies the conditions, directors should consider the appropriate alternative rather than continuing with the strike-off application.
What Should You Do Before Closing A Company?
Closing down the business properly before applying is one of the most important parts of the process.
Directors should first identify everything still owned or owed by the company and resolve as much as possible before dissolution.
Important tasks can include:
- Collect Outstanding Payments: Recover money owed by customers and other parties.
- Pay Creditors: Settle suppliers, lenders, landlords and other outstanding liabilities.
- Deal With Employees: Pay final wages and follow the applicable rules where redundancies are required.
- Complete Tax Responsibilities: Prepare final accounts and the final Company Tax Return and pay outstanding Corporation Tax.
- Close PAYE Arrangements: Tell HMRC when the company stops employing people and complete the necessary final payroll reporting.
- Cancel VAT Registration: A VAT-registered company that stops trading may need to deregister and submit its final VAT return.
- Deal With Company Assets: Transfer or distribute equipment, cash, investments, intellectual property and other assets before dissolution.
- Close Company Bank Accounts: Deal with remaining money before the company ceases to exist.
- Transfer Domain Names And Other Digital Assets: Company-owned domains and other property should be dealt with before dissolution.
This stage should not be rushed. Assets that remain in the company when it is dissolved can pass to the Crown. That can include money remaining in a bank account and payments received after dissolution, such as certain refunds.
How To Close A Company On Companies House Step By Step?
Once the company is ready for closure and meets the eligibility requirements, the voluntary strike-off process can begin.
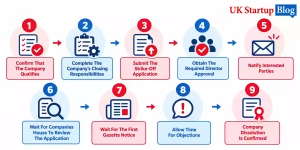
1. Confirm That The Company Qualifies
Check that the business meets the voluntary strike-off requirements, including the restrictions relating to trading, company name changes, insolvency proceedings and creditor arrangements.
2. Complete The Company’s Closing Responsibilities
Deal with creditors, employees, tax obligations, remaining contracts, bank accounts and assets before applying.
3. Submit The Strike-Off Application
The quickest and lower-cost option in 2026 is normally the Companies House online service. Companies that cannot apply online can use the paper DS01 form.
4. Obtain The Required Director Approval
A majority of the company’s directors must approve the strike-off application. If there are two directors, both must approve it. If there is only one director, that director can apply.
5. Notify Interested Parties
Within seven days of making the application, copies must be sent to relevant parties who may be affected.
These can include:
- Shareholders
- Creditors
- Employees
- Pension Fund Managers Or Trustees
- Directors Who Did Not Sign The Application
Relevant parties who enter one of these categories after the application may also need to be notified while the strike-off process remains active.
6. Wait For Companies House To Review The Application
Companies House checks the application. Incorrect company details, missing director approval or problems with a paper DS01 can delay the process.
7. Wait For The First Gazette Notice
If the application is accepted, notice of the proposed strike-off is published in the appropriate Gazette.
This publicly announces that Companies House intends to remove the company from the register.
8. Allow Time For Objections
Creditors and other eligible interested parties are given an opportunity to object.
If there is no reason to stop the process, Companies House can proceed with the strike-off after the required Gazette notice period.
9. Company Dissolution Is Confirmed
A second Gazette notice is published when the company has been dissolved. From this point, the company no longer legally exists.
What Happens After You Submit The Strike-Off Application?
Submitting the application does not immediately close the company.
Companies House first checks whether the application appears to satisfy its requirements.
If accepted, the proposed strike-off becomes part of the public company record and notice is published in the Gazette.
The Gazette notice allows creditors and other interested parties to become aware of the proposed closure and raise an objection where appropriate.
A typical process looks like this:
| Stage | What Happens |
| Application Submitted | Directors submit the voluntary strike-off request |
| Companies House Review | The application is checked |
| Interested Parties Notified | Copies are sent to affected parties within the required period |
| First Gazette Notice | Proposed strike-off becomes public |
| Objection Period | Creditors and other eligible parties can object |
| Strike-Off | Companies House removes the company if there is no reason to stop the process |
| Final Gazette Notice | Dissolution is formally recorded |
Directors must continue monitoring the situation while the application is active. If circumstances change and the company becomes ineligible for strike-off, the application may need to be withdrawn.
What Can Stop Or Cancel The Company Closure Process?
A voluntary strike-off can be interrupted at several stages.
Common reasons include:
- A Creditor Objects: Someone owed money by the company may ask Companies House to stop the strike-off.
- HMRC Has Outstanding Matters: Unresolved Corporation Tax, VAT, PAYE or other tax issues can result in an objection.
- The Company Starts Trading Again: Resuming normal business activity can make the company ineligible for voluntary strike-off.
- The Company Becomes Insolvent: If the company can no longer pay its debts, directors may need to consider an insolvency procedure.
- Legal Proceedings Begin: Existing or new legal claims can affect whether the company can be dissolved.
- The Company No Longer Meets the Eligibility Conditions: Changes during the process can require the directors to withdraw the application.
- The Application Contains Errors: Incorrect company information, missing signatures or an incorrect paper application fee can delay or prevent acceptance.
- The Directors Change Their Minds: A strike-off application can be voluntarily withdrawn while the company remains on the register.
If the company becomes ineligible after applying, directors should not simply wait for Companies House to discover the issue. The strike-off application should be withdrawn.
What Happens If HMRC Or A Creditor Objects?
Creditors and other interested parties can object after the proposed strike-off has been published in the Gazette if they have valid grounds.
A creditor might object because the company still owes money or because legal action is being taken against it. HMRC may also object where tax matters or liabilities remain unresolved.
Supporting evidence is normally required when making an objection.
If Companies House accepts the objection, the company will generally not be struck off for another six months. This gives the parties time to resolve the issue or continue appropriate legal action.
During this period, the directors may need to:
- Pay Or Resolve The Outstanding Debt
- Complete Outstanding Tax Requirements
- Resolve The Dispute With The Creditor
- Provide Any Required Information
- Use A Different Closure Procedure If Strike-Off Is No Longer Appropriate
An objection does not necessarily mean the company can never be closed. Once the underlying problem has been resolved, the strike-off process may be able to continue.
There is also an important change approaching in December 2026.
From 1 December 2026, Companies House plans to require objections to limited-company strike-offs to be submitted through its online objection service rather than through the existing email route.
How Much Does It Cost And How Long Does It Take In 2026?
Companies House changed a number of filing fees from 1 February 2026.
For voluntary strike-off in 2026:
| Application Method | Companies House Fee |
| Online Strike-Off Application | £13 |
| Paper Strike-Off Application | £18 |
The online service is generally faster and includes checks that can reduce the likelihood of completing the application incorrectly.
The paper DS01 process usually takes longer and errors can result in the form being returned.
A straightforward voluntary strike-off often takes around three months from application to dissolution, although there is no guarantee that every company will close within that period.
The Gazette objection period itself generally runs for at least two months after publication of the proposed strike-off notice.
The overall process can take longer if:
- Companies House Rejects Or Returns The Application
- A Creditor Raises An Objection
- HMRC Has Unresolved Tax Matters
- Company Details Are Incorrect
- The Directors Need To Withdraw And Reapply
- Legal Or Insolvency Issues Arise
Businesses using liquidation instead of voluntary strike-off will usually face considerably higher costs because professional insolvency services are required.
What Happens After The Company Is Dissolved?
Once the final Gazette notice confirms dissolution, the company stops existing as a legal entity.
It can no longer trade, enter new contracts or operate its previous company bank account.
Any assets that were not dealt with before dissolution can pass to the Crown. This is why directors should identify and distribute or transfer company property before the company disappears from the register.
Dissolution also does not automatically make every historic issue disappear.
Creditors and other eligible parties can, in certain circumstances, seek restoration of the company so that claims or unresolved matters can be pursued.
Directors should also retain appropriate business records after closure.
General business documents such as bank statements, invoices and receipts should normally be kept for seven years after the company is struck off.
A company that was voluntarily struck off cannot normally use the simpler administrative restoration procedure.
Restoring a voluntarily dissolved company generally requires a court order, subject to the applicable eligibility requirements and time limits.
FAQs
Can You Close A Company That Owes Money?
You should normally settle outstanding debts before applying for voluntary strike-off. Creditors can object if money is still owed.
Can You Close A Company That Has Never Traded?
Yes. A company that has never traded can usually be struck off if it meets the Companies House eligibility requirements.
Can HMRC Stop A Company From Being Struck Off?
Yes. HMRC can object if there are unpaid taxes, missing returns or unresolved tax matters.
Why Has My Voluntary Strike-Off Been Suspended?
Strike-off may be suspended if a creditor, HMRC or another eligible party raises a valid objection.
Can You Cancel A Strike-Off After Applying?
Yes. Directors can withdraw a voluntary strike-off application before the company is dissolved.
How Long Does It Take To Close A Company On Companies House?
A straightforward voluntary strike-off often takes around three months, although objections or application issues can make the process longer.
Can A Dissolved Company Be Restored?
Yes. A voluntarily dissolved company can potentially be restored, although this generally requires a court application.
Blogger | Business Writer | Sharing startup advice on UK business blogs
Related Articles in Startup
View All →
Newscivil Com: Can This Digital News Platform Help UK Startups Spot Emerging Trends?
For startup founders, staying informed is no longer simply about reading the business pages each morning. Artificial intelligence, changing consumer habits, technology developments, government decisions and wider social…
Meet the Startup Turning Screen Time Into a New Way to Make Money
Britain does not exactly have a shortage of side hustles. You can deliver takeaways, sell clothes online, start freelancing, walk dogs, tutor in the evenings or attempt to…
8 Best Coworking Spaces for Bootstrapped London Startups to Launch and Scale in 2026
Bootstrapped founders don’t have the luxury of a fitted-out HQ from day one. What you need is a London coworking space that flexes with you: a hot desk…