Top 10 Guaranteed Approval Credit Cards for Bad Credit in the UK 2026

UK Startup Blog Archive
Table of Contents
Last Updated on 09.09.2026
If you have a poor credit history, previous missed payments or very little UK credit history, getting accepted for a mainstream credit card can be difficult. However, several UK lenders offer credit-builder cards specifically designed for people who may not qualify for their standard products.
It is important to clear up one point immediately. There is no genuinely guaranteed approval credit card in the UK where every applicant is accepted regardless of their circumstances.
Lenders must assess creditworthiness and affordability before entering into a regulated credit agreement.
What people usually mean by “guaranteed approval credit cards” are cards offering soft-search eligibility checks, pre-approval or a clear indication of acceptance before a full application.
What Are Guaranteed Approval Credit Cards?
“Guaranteed approval credit card” is primarily a search term rather than an official type of UK credit card.
In practice, credit card providers cannot simply ignore affordability and creditworthiness. FCA rules require lenders to make a reasonable creditworthiness assessment before entering into a regulated credit agreement.
What does exist are credit-builder or bad-credit cards with features intended to make applying less risky, including:
- Soft-search eligibility checkers
- Pre-application acceptance indicators
- Lower starting credit limits
- Products designed for limited or damaged credit histories
- Credit-building tools
- Mobile spending and payment alerts
A soft eligibility check normally does not leave the same visible footprint as a full credit application. If you then proceed with a full application, the provider will normally carry out further checks.
Who Can Benefit From A Credit-Builder Card?
Credit-builder cards can be useful for several groups.
- People With Poor Credit: Previous late payments, defaults, high borrowing or other problems on your credit report can restrict access to mainstream cards. Specialist credit-builder providers may still consider your application, although acceptance depends on your current circumstances.
- People With Limited Credit History: You can also struggle to obtain credit simply because lenders do not have enough information about how you manage borrowing. This can affect young adults and people who have recently moved to the UK.
- People Rebuilding Their Credit: Regularly making payments on time and staying within your agreed credit limit can help establish positive repayment behaviour. MoneyHelper notes that building a history of paying borrowing on time can improve the way lenders assess your creditworthiness.
- People Previously Rejected For Mainstream Cards: A rejection does not necessarily mean that every lender will turn you down.
However, repeatedly applying for different cards is usually a poor strategy. Eligibility checkers provide a safer way to see which products are realistically available before submitting full applications.
If a credit card is not appropriate, borrowers considering another form of finance should also understand how a loan with bad credit works before taking on additional borrowing.
Top 10 Guaranteed Approval Credit Cards For Bad Credit In The UK
The products below are not ranked purely by APR because the most suitable card depends on your credit history, eligibility, income, existing debt and how you intend to use the account.
Rates and limits shown are current advertised figures checked in September 2026. Your personal offer may be different.
1. Tesco Bank Foundation Credit Card
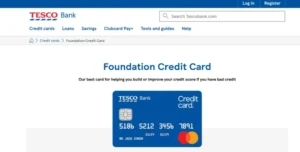
The Tesco Bank Foundation Credit Card is specifically positioned as a credit-builder card and currently has one of the lower representative APRs among products aimed at rebuilding credit.
- Representative APR: 29.9% variable
- Starting Credit Limit: £200 to £1,500
- Annual Fee: None stated
- Eligibility Check: Available without affecting your credit score
Tesco Bank also provides access to CreditView from TransUnion for three years from account opening, allowing customers to monitor their credit score. Cardholders may be considered for optional credit-limit increases when the account is managed responsibly.
Best For: People wanting a lower-APR credit-builder card with credit monitoring.
2. Zable Credit Card
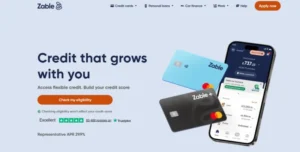
Zable is designed for people building or rebuilding their credit history and uses more than a traditional credit score when assessing some applications.
- Representative APR: 29.9% variable
- Credit Limit: Up to £4,000 across its current card range
- Eligibility Check: Soft check available
- Digital Wallets: Apple Pay and Google Pay supported for eligible customers
Zable states that applicants can use banking history through Open Banking to potentially improve their approval chances. Its eligibility checker can provide a decision without affecting the applicant’s credit score.
The card can also be relevant for people who have recently moved to the UK and have not yet established a substantial UK credit history.
Best For: App-based management, limited UK credit history and Open Banking assessment.
3. HSBC Classic Credit Card
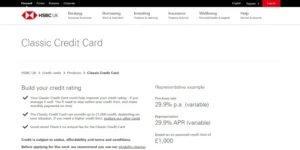
The HSBC Classic Credit Card is explicitly designed to help customers start building or improve their credit rating.
- Representative APR: 29.9% variable
- Maximum Credit Limit: Up to £1,000
- Annual Fee: £0
- Availability: Existing HSBC customers
- Minimum UK Taxable Income Or Pension: £6,800 a year under current criteria
HSBC recommends using its eligibility checker before applying. The card has deliberately limited borrowing capacity compared with many mainstream cards, which can help customers avoid taking on a large balance while establishing their repayment history.
Best For: Existing HSBC customers who want to establish or repair their credit record.
4. Capital One Classic Card
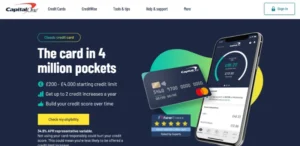
Capital One’s Classic Card remains one of the better-known UK credit-builder products.
- Representative APR: 34.9% variable
- Starting Credit Limit: £200 to £4,000
- Annual Fee: None
- Eligibility Check: Available without affecting your credit score
Capital One specifically markets the Classic Card towards people with bad credit or those wanting to build their credit history. Its current starting credit limits can range from £200 to £4,000 depending on the applicant’s circumstances.
Capital One may also offer eligible customers credit-limit increases, although increasing a limit should not be treated as a reason to increase spending.
Best For: Straightforward credit building with flexible limits.
5. Luma Purchase Card
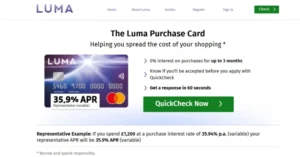
Luma is another product aimed at people who may have a weaker or relatively short credit history.
- Representative APR: 35.9% variable
- Credit Limit: £200 to £4,000
- Purchase Offer: Up to three months at 0% depending on eligibility
- Eligibility Check: QuickCheck available
Luma states that applicants may be considered even when they are new to credit or have issues such as CCJs on their credit history. That does not mean someone with a CCJ will automatically be accepted.
The short introductory purchase offer may be useful for qualifying applicants, but the standard APR becomes much more important if the balance is not repaid during an interest-free period.
Best For: Applicants with limited credit history or previous credit problems who want to check eligibility before applying.
6. Vanquis Credit Builder Credit Card
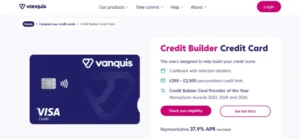
The Vanquis Credit Builder Credit Card is designed specifically for customers trying to build their credit score.
- Representative APR: 37.9% variable
- Credit Limit: £250 to £2,500
- Eligibility Check: Available without affecting your credit score
- Account Management: Vanquis mobile app
Vanquis states that applicants must generally be aged 18 or over, have a regular income and be permanent UK residents. Current exclusions include being bankrupt or having an active IVA.
The card also comes with a personalised limit based on the lender’s assessment of the applicant’s circumstances.
Best For: People rebuilding their credit who want a specialist credit-builder provider.
7. Ocean Credit Card
Ocean’s current credit-builder offering is aimed at people who have a poor, limited or developing credit history.
- Representative APR: 39.9% variable
- Credit Limit: Up to £8,000 on its current credit-builder product
- Eligibility Check: Soft search
- Decision Time: Usually around 60 seconds
- Lender: Capital One
Ocean Finance acts as the credit broker and Capital One is the exclusive lender behind the Ocean Credit Card.
The eligibility check does not affect your credit score, allowing you to establish whether the card is a realistic option before making a full application.
Best For: Applicants who want a quick eligibility indication before applying.
8. Aqua Classic Card
The Aqua Classic remains one of the UK’s major credit-builder cards, although its APR is now higher than the figure previously shown in this article.
- Representative APR: 39.9% variable
- Initial Credit Limit: £250 to £1,500
- Annual Fee: None
- Eligibility Check: SafeCheck available
- Credit Score Access: Available through the Aqua app
Aqua positions the Classic specifically as a card for people with bad or poor credit history. Responsible account management can help establish a stronger credit history, while missed payments can have the opposite effect.
Aqua’s SafeCheck allows prospective applicants to assess their eligibility without affecting their credit score.
Best For: Credit rebuilding with app-based score monitoring and support.
9. thimbl Credit Builder Credit Card
The thimbl Credit Builder Credit Card continues to accept applications across a wide range of credit profiles, but its current representative APR is substantially higher than the figure previously shown on this page.
- Representative APR: 48.9% variable
- Starting Credit Limit: £200 to £2,000
- Eligibility Check: Soft search
- Minimum Monthly Net Income: Current eligibility criteria include at least £800
- Provider: Credit is provided by Lendable
thimbl currently allows customers to check eligibility before submitting a full application. Its advertised representative APR is 48.9%, not the 34.5% previously shown in this article.
Because of the comparatively high rate, carrying a balance for a long period could become expensive.
Best For: Applicants who have already established some credit but are still rebuilding their overall profile.
10. 118 118 Money Credit Card
The 118 118 Money Credit Card is designed for borrowers with less-than-perfect credit.
- Representative APR: 49.0% variable
- Credit Limit: £250 to £2,000
- Eligibility Check: Available without affecting your credit score
- Interest-Free Purchases: Up to 51 days when qualifying balances are repaid appropriately
118 118 Money distinguishes between guaranteed rates and credit limits after eligibility has been assessed and guaranteed approval itself. Applicants are still subject to status, affordability and credit checks.
Its current eligibility criteria include restrictions relating to recent arrears, defaults and CCJs, so this should not be interpreted as a card that automatically accepts every person with poor credit.
Best For: People rebuilding credit who want to know their potential limit before completing an application.
Credit-Builder Card Comparison For 2026
| Credit Card | Representative APR | Advertised Credit Limit | Main Benefit |
| Tesco Bank Foundation | 29.9% Variable | £200–£1,500 | Credit monitoring and relatively low APR |
| Zable | 29.9% Variable | Up To £4,000 | Open Banking and app-based management |
| HSBC Classic | 29.9% Variable | Up To £1,000 | Designed to build credit rating |
| Capital One Classic | 34.9% Variable | £200–£4,000 | Established credit-builder option |
| Luma Purchase Card | 35.9% Variable | £200–£4,000 | Accessible eligibility criteria |
| Vanquis Credit Builder | 37.9% Variable | £250–£2,500 | Specialist credit building |
| Ocean Credit Builder | 39.9% Variable | Up To £8,000 | Quick soft eligibility check |
| Aqua Classic | 39.9% Variable | £250–£1,500 | Credit-building tools and score access |
| thimbl Credit Builder | 48.9% Variable | £200–£2,000 | Soft-search eligibility check |
| 118 118 Money | 49.0% Variable | £250–£2,000 | Potential limit shown before application |
Important: Representative APR does not necessarily mean that every successful applicant will receive that rate. For representative APR advertising, at least 51% of successful applicants must receive the advertised rate or better.
Which Credit Cards Were Removed From The Previous List?
Several products included in the older version should no longer appear in a ranking of credit cards.
- Lending Stream: Lending Stream primarily provides short-term instalment loans. It should not have been described as a credit card.
- Drafty: Drafty provides a revolving line of credit rather than a conventional credit card. Comparing its APR directly with credit-builder cards created a misleading like-for-like comparison.
- Easy Loans: The previously listed Easy Loans product could not be treated as a clearly verified current UK credit-builder credit card for this comparison.
Replacing these entries with Tesco Bank Foundation, Vanquis Credit Builder, 118 118 Money and HSBC Classic makes the 2026 list more representative of actual credit-card products currently available.
What Should You Look For In A Bad-Credit Credit Card?
Representative APR
Credit-builder products generally have relatively high APRs.
If you clear your purchase balance in full every month, you can often avoid purchase interest. If you expect to carry a balance, however, even a relatively small difference in APR can have a meaningful effect on the total cost.
Eligibility Checker
This is particularly important if your credit record is already weak.
A soft-search eligibility checker gives you an indication of your chances without making repeated full applications.
Credit Limit
Do not automatically assume a higher credit limit is better.
A lower limit can make spending easier to control while you establish a stronger repayment history.
Fees
Check for:
- Annual Fees
- Late Payment Fees
- Cash Withdrawal Fees
- Foreign Transaction Charges
- Balance Transfer Fees
The representative APR does not necessarily capture every charge that could arise from the way you use the card.
Credit-Building Features
Some providers give customers access to their credit score, payment reminders, spending alerts or personalised credit-building support.
These tools can be more valuable than rewards or cashback when your main objective is repairing your credit history.
How Can A Credit-Builder Card Improve Your Credit Rating?
A credit card does not improve your credit score simply because you have been approved.
What matters is how you manage it.
Make Every Payment On Time
Missing or making late payments can be reported to credit reference agencies and may make borrowing more difficult.
Setting up a Direct Debit for at least the minimum payment can reduce the risk of accidentally missing the due date.
Pay In Full Where Possible
Paying only the minimum can keep you in debt for considerably longer and increase the interest you pay.
Where affordable, clearing the entire statement balance each month is generally the cheapest way to use a credit-builder card.
Keep Credit Utilisation Low
Credit utilisation compares how much revolving credit you are using with your available limits.
Experian currently recommends keeping utilisation low, particularly below around 25%, where possible.
For example, a £200 balance against a £1,000 total limit represents 20% utilisation.
Avoid Repeated Credit Applications
Full credit applications normally result in hard searches.
Multiple applications over a short period can make you appear increasingly dependent on borrowing, so checking eligibility first is usually preferable.
Check Your Credit Reports
Review the information held by the major credit reference agencies and correct any inaccurate accounts, addresses or payment information.
Your credit score itself is only one part of the lending decision. Lenders can use their own scoring systems alongside your income, debts, affordability and information in your credit file.
Are Credit-Builder Cards Better Than 0% Cards?
Not necessarily. They solve different problems.
A credit-builder card is mainly designed to give someone with a weaker or limited credit record an opportunity to establish positive borrowing behaviour.
A 0% card is primarily designed to reduce borrowing costs for applicants who qualify for promotional offers.
If your credit rating has already improved and you are paying interest on existing card debt, a 0% balance transfer credit card could potentially reduce interest costs.
Similarly, someone with stronger eligibility who needs to spread the cost of a planned purchase may find a 0% interest credit card more cost-effective than borrowing on a high-APR credit-builder card.
Pros And Cons Of Credit Cards For Bad Credit
Pros:
- More Accessible: Designed for people who may struggle to obtain mainstream cards
- Credit Building: Responsible repayment behaviour can contribute to a stronger credit history
- Soft Eligibility Checks: Many providers let you assess your chances before applying
- Credit Monitoring: Some cards provide free score tracking and alerts
- Section 75 Protection: Qualifying credit-card purchases can receive protection under Section 75 of the Consumer Credit Act
Cons:
- Higher APRs: Current representative rates on specialist products can approach 50%
- Lower Starting Limits: Some applicants may only receive a few hundred pounds of available credit
- Acceptance Is Still Conditional: Poor credit does not automatically mean approval
- Expensive Long-Term Borrowing: Carrying a balance can result in substantial interest charges
- Further Damage Is Possible: Missed payments or exceeding limits can worsen your credit position
What If You Are Rejected?
Do not immediately submit applications to several other lenders.
Instead:
- Check Your Credit Reports for incorrect information
- Ask The Lender whether it can explain the rejection
- Review Existing Debt and reduce balances where possible
- Register On The Electoral Roll at your current address
- Wait Before Reapplying if you have recently made several applications
- Use Soft Eligibility Checks before your next full application
MoneyHelper specifically advises consumers not to keep reapplying after being declined because repeated applications can damage their credit profile.
If you are already struggling to meet existing repayments, taking out another credit card might make the situation worse. Free debt support is available through organisations such as MoneyHelper, StepChange, Citizens Advice and National Debtline.
Conclusion
There is no universal guaranteed approval credit card for bad credit in the UK, but there are significantly more options for people with poor or limited credit histories than the term might suggest.
In 2026, cards such as Tesco Bank Foundation, Zable, HSBC Classic, Capital One Classic, Luma, Vanquis, Ocean, Aqua, thimbl and 118 118 Money provide different routes into credit building.
The key is not finding the card most likely to say yes at any cost.
Instead, check eligibility without harming your credit score, compare the actual APR and credit limit offered to you, make sure repayments are affordable and use the card primarily as a tool for establishing a stronger repayment history.
If possible, pay the statement balance in full every month. A high-APR credit-builder card becomes considerably more expensive when it is used for long-term borrowing.
Frequently Asked Questions
Are There Any 100% Guaranteed Approval Credit Cards In The UK?
No legitimate lender can promise unconditional acceptance regardless of your financial circumstances. Credit providers must assess creditworthiness and affordability before granting regulated credit.
Which Credit Card Is Easiest To Get With Bad Credit?
There is no single easiest card because every provider uses different eligibility criteria. Aqua, Capital One, Vanquis, Ocean, Luma, Zable, thimbl and 118 118 Money all offer products aimed at people building or rebuilding credit.
Can I Check Whether I Will Be Accepted Without Affecting My Credit Score?
Yes. Many providers use soft-search eligibility checkers that do not affect your credit score in the same way as a full application.
What Is The Lowest APR Credit-Builder Card In This List?
Tesco Bank Foundation, Zable and HSBC Classic currently advertise representative APRs of 29.9% variable. The APR you personally receive can still depend on the provider and your circumstances.
Can I Get A Credit Card If I Have A CCJ?
Potentially. Some specialist providers may consider applicants with previous credit problems, but a CCJ can reduce your chances of approval. Luma, for example, states that its eligibility criteria can accommodate applicants with CCJs, subject to assessment.
Will A Credit-Builder Card Improve My Credit Score?
It can contribute to a stronger credit history if you make payments on time, remain within your limit and manage borrowing responsibly. Missed payments can instead damage your credit profile.
How Much Credit Utilisation Should I Use?
Lower utilisation is generally preferable. Experian currently suggests keeping utilisation below around 25% where possible, although lenders use many other factors when assessing applications.
Should I Pay A Credit-Builder Card Off In Full?
If you can afford to, paying your purchase balance in full each month is usually the most cost-effective approach because it can prevent purchase interest from being charged.
Blogger | Business Writer | Sharing startup advice on UK business blogs
Related Articles in Finance
View All →
If I Take Home £1,600 a Month, What Is My Salary in the UK?
If an employee takes home £1,600 per month in the UK, their estimated gross salary is approximately £21,780 per year. This is equal to about £1,815 per month…
Why the Two Year Accounts Rule is Not Actually a Rule?
Ask most new business owners when they can first apply for a mortgage and the answer comes back the same way every time: two years of accounts, minimum,…

Snap-on Franchise Cost: Fees, Investment and Earnings
The Snap-on franchise cost in the UK is currently quoted at £166,597 to £168,487 for the franchise investment, with Snap-on stating that a new franchisee may need to…