How Much Is Capital Gains Tax in the UK: 18% and 24% Rates Explained

UK Startup Blog Archive
Table of Contents
Capital Gains Tax (CGT) is charged on the profit you make when you sell or dispose of certain assets that have increased in value.
You do not pay tax on the full selling price. Instead, CGT normally applies to the gain after eligible costs, losses and your annual tax-free allowance have been taken into account.
For the 2026/27 tax year, individuals generally pay Capital Gains Tax at 18% or 24%, depending on their taxable income and how much of the gain falls within the basic Income Tax band.
The annual exempt amount for most individuals remains £3,000.
Understanding how tax is calculated in the UK can also help when working out how your taxable income affects the CGT rate applied to a disposal.
How Much CGT Could You Pay in the 2026/27 Tax Year?
The amount of Capital Gains Tax you pay depends mainly on your taxable income, the size of your taxable gain and whether any specific relief applies.
For disposals from 6 April 2026, the main CGT rates for individuals are 18% and 24%. Higher and additional rate Income Tax taxpayers generally pay 24% on taxable gains.
Basic rate taxpayers may pay 18% on the portion of their gain that falls within the unused basic rate band and 24% on the remainder.
| Circumstance | 2026/27 CGT Rate |
| Gain Falling Within Available Basic Rate Band | 18% |
| Gain Above Available Basic Rate Band | 24% |
| Higher Or Additional Rate Taxpayer | 24% |
| Trustees And Personal Representatives | 24% |
| Qualifying Business Asset Disposal Relief Gain | 18% |
Business Asset Disposal Relief changed again from 6 April 2026. Qualifying gains are now taxed at 18%, compared with 14% for qualifying disposals made during 2025/26.
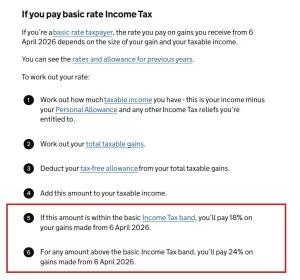
The GOV.UK Capital Gains Tax rates page confirms the 18% and 24% individual rates applying from 6 April 2026.
What Is the Capital Gains Tax Allowance for 2026/27?
The Capital Gains Tax annual exempt amount is £3,000 for most individuals in 2026/27. This means the first £3,000 of your net taxable gains for the tax year can generally be covered by the allowance.
Most other trustees have an annual exempt amount of £1,500, while trustees for disabled people can qualify for the £3,000 amount.
The £3,000 allowance applies to your overall eligible gains for the tax year rather than separately to every asset you sell.
For example, if you make gains of £2,000 from shares and £5,000 from another taxable investment, your combined gains are £7,000.
Assuming there are no allowable losses or other adjustments, deducting the £3,000 annual exempt amount would leave £4,000 potentially subject to CGT.
The allowance has fallen considerably from previous years. It was £12,300 in 2022/23 and £6,000 in 2023/24 before falling to £3,000 from 2024/25 onwards.
How Is Capital Gains Tax Calculated?
CGT is based on your gain, not simply the amount of money you receive when selling an asset.
A straightforward calculation generally starts with:
Selling Price − Purchase Cost − Allowable Costs = Capital Gain
You then consider eligible capital losses and the annual exempt amount before applying the appropriate CGT rate.
For basic rate taxpayers, your taxable income also matters. HMRC requires you to work out your taxable income, calculate your taxable gains, deduct your CGT allowance and then add the remaining gain to your taxable income.
The portion remaining within the basic Income Tax band is generally taxed at 18%, while the portion above it is generally taxed at 24%.
For example, suppose you have taxable income of £20,000 and a taxable gain before the annual exemption of £12,600.
Deducting the £3,000 allowance leaves £9,600. HMRC’s 2026/27 example places the combined amount of £29,600 within the £37,700 basic rate band, producing CGT of £1,728 at 18%.
How Much Capital Gains Tax Would You Pay on Different Gains?
The exact amount cannot be determined from the gain alone because your income, losses and available reliefs can change the calculation.
The following examples assume:
- Taxable Income: £20,000
- Annual Exempt Amount: £3,000
- No Capital Losses: No previous or current-year losses are used
- No Additional Reliefs: The gains do not qualify for a special CGT relief
Using the £37,700 basic rate band shown in HMRC’s 2026/27 CGT calculation examples gives these illustrative figures.
| Total Gain | Gain After £3,000 Allowance | Illustrative CGT |
| £10,000 | £7,000 | £1,260 |
| £50,000 | £47,000 | £10,218 |
| £100,000 | £97,000 | £22,218 |
For the £10,000 example, the £7,000 taxable gain remains within the available basic rate band, so it is taxed at 18%.
With a £50,000 gain, £17,700 falls within the remaining basic rate band and is taxed at 18%. The remaining £29,300 is taxed at 24%, producing £10,218 of CGT.
With a £100,000 gain, £17,700 is taxed at 18% and the remaining £79,300 at 24%, producing £22,218.
These are examples rather than personalised tax calculations. A different income level, allowable loss or tax relief could change the final bill significantly.
What Costs Can You Deduct Before Paying Capital Gains Tax?
Certain costs connected with acquiring, improving and disposing of an asset can reduce the gain on which CGT is calculated.
For property, HMRC allows eligible buying, selling and improvement costs to be deducted.
Examples can include estate agent fees, solicitors’ fees and qualifying improvement expenditure such as an extension. Ordinary maintenance and decoration do not normally count as capital improvement costs.
Depending on the asset, deductible costs can include:
- Buying Costs: Certain legal fees, professional costs and relevant taxes paid when acquiring the asset
- Selling Costs: Solicitor, broker, estate agent, valuation and advertising fees where eligible
- Improvement Costs: Capital expenditure that enhances the asset and is still reflected in it when it is sold
- Share Transaction Costs: Eligible broker fees and Stamp Duty Reserve Tax connected with acquiring or selling shares
For shares, HMRC specifically allows certain buying and selling costs, including stockbroker fees and eligible Stamp Duty Reserve Tax.
Accurate records therefore matter. Purchase contracts, invoices, legal bills and evidence of improvement expenditure can all be important when establishing the correct gain.
Which Assets Are Subject to Capital Gains Tax?
CGT can apply to several types of assets when you sell, exchange, give away or otherwise dispose of them.
Property
You may have to pay CGT when disposing of buy-to-let properties, land, business premises and inherited property that has risen in value after you inherited it.
Your main home can usually qualify for Private Residence Relief when the relevant conditions are satisfied.
Shares And Investments
Shares held outside an ISA or PEP can be subject to CGT. Units in certain investment funds and other investments can also fall within the rules. Shares held within an ISA are generally sheltered from CGT.
Cryptocurrency
Selling cryptocurrency is not the only transaction that can create a taxable disposal.
Exchanging one cryptoasset for another, using crypto to pay for goods or services, or giving it to another person can potentially create a CGT event. Gifts to a spouse, civil partner or charity are subject to separate rules.
Business Assets
Sole traders and business partners may face CGT when disposing of qualifying business assets. This can include property, shares and other assets connected with the business.
Different rules apply when the asset belongs to a limited company rather than an individual.
Which Gains Are Exempt From Capital Gains Tax?
Not every profitable disposal creates a CGT charge.
HMRC identifies several assets and circumstances where CGT may not apply.
These include:
- ISA Investments: Capital gains arising on investments held within an ISA are generally tax-free
- Your Main Home: Full Private Residence Relief may remove CGT where all qualifying conditions are satisfied
- UK Government Gilts: Gains on eligible UK government gilts and Premium Bonds are not normally subject to CGT
- Personal Cars: Private cars are normally outside CGT, although different treatment can apply where a vehicle has been used for business
Lottery, betting and pools winnings are also outside Capital Gains Tax.
Private Residence Relief deserves particular attention.
Full relief generally applies where the property has been your only or main home throughout ownership, has not been partly let out beyond permitted circumstances, has not been used exclusively for business and meets the other qualifying conditions.
Can Capital Losses Reduce Your CGT Bill?
Yes. An allowable capital loss can reduce the gains on which you pay Capital Gains Tax.
Losses from the same tax year are generally deducted from gains made during that year.
If taxable gains remain above the annual exempt amount, qualifying unused losses brought forward from previous tax years can also be used.
You do not necessarily have to claim a capital loss immediately. HMRC normally allows you to claim it within four years after the end of the tax year in which you disposed of the asset.
For example, if you make a £20,000 gain on one chargeable asset but an allowable £5,000 loss on another during the same tax year, the loss can reduce your overall gain before the annual exempt amount and CGT calculation are considered.
Losses should therefore be recorded even when you have no immediate CGT liability because they may become valuable in a later tax year.
How Much Capital Gains Tax Do You Pay When Selling a Business?
Selling a business can create substantial capital gains, particularly where you sell business assets or shares that have increased significantly in value.
However, some entrepreneurs may qualify for Business Asset Disposal Relief, previously known as Entrepreneurs’ Relief.
From 6 April 2026, qualifying gains covered by Business Asset Disposal Relief are taxed at 18%. The lifetime limit for qualifying gains remains £1 million.
For a sole trader or business partner selling all or part of a business, the qualifying conditions generally need to have been met for at least two years before disposal.
Shareholders face additional requirements relating to their position in the company, its trading activities and, in many cases, their ownership and voting rights.
For a qualifying founder making a large disposal, checking eligibility before the transaction takes place can therefore make a major difference to the final tax calculation.
Do Limited Companies Pay Capital Gains Tax on Asset Sales?
A UK limited company does not normally pay personal Capital Gains Tax when it sells one of its own assets.
Instead, the company generally pays Corporation Tax on the chargeable gain. Assets can include land, property, machinery, equipment and shares owned by the company.
This makes the distinction between an asset sale and a share sale particularly important.
If a company sells an asset, the resulting chargeable gain normally forms part of the company’s Corporation Tax position. Businesses dealing with this can also check the practical requirements for paying Corporation Tax.
If an individual shareholder instead sells their personally owned shares in the company, Capital Gains Tax may apply to that individual.
Business Asset Disposal Relief may reduce the rate to 18% where all the qualifying conditions are satisfied.
The tax outcome can therefore be very different depending on how a business sale is structured.
How Do Gifts And Transfers Affect Capital Gains Tax?
Giving an asset away does not automatically mean there is no Capital Gains Tax.
For gifts to people other than a spouse, civil partner or charity, you may need to use the asset’s market value at the date of the gift when calculating the gain.
Market value can also be required where an asset is deliberately sold for less than it is worth to help the buyer.
Transfers between spouses and civil partners can normally take place on a no gain, no loss basis when the relevant conditions apply.
This means CGT is generally deferred rather than immediately charged.
There are also extended rules for separating couples.
For disposals on or after 6 April 2023, qualifying no-gain, no-loss transfers may generally be made until the earlier of the end of the third tax year after the couple ceased living together or the legal divorce or dissolution.
Transfers made under certain formal divorce or separation agreements can receive no-gain, no-loss treatment without that three-year time limit.
Gifts to charity are also generally outside CGT, although special rules can apply if the charity pays you for the asset.
When Do You Need to Report And Pay Capital Gains Tax?
You are responsible for determining whether you have taxable gains. HMRC does not simply issue a CGT bill automatically.
The reporting deadline depends particularly on what you disposed of.
For UK residential property with a completion date on or after 27 October 2021, any CGT due generally has to be reported and paid within 60 days of completion.
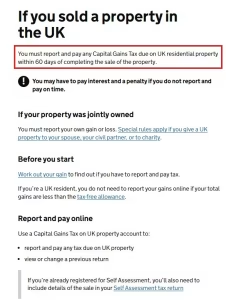
The GOV.UK property reporting page confirms that CGT due on UK residential property generally has to be reported and paid within 60 days of completion.
For other taxable gains, reporting may be handled through Self Assessment or, where eligible, HMRC’s real-time Capital Gains Tax service.
HMRC states that eligible users of the real-time service may report by 31 December in the tax year following the disposal.
Sole traders and business owners managing CGT alongside other liabilities may also need to coordinate the figures with their wider small business tax returns.
The payment process itself varies depending on the type of disposal, so understanding how to pay Capital Gains Tax can help once the gain and reporting route have been established.
How Can You Legally Reduce Capital Gains Tax in the UK?
Tax planning should take place before an asset is sold where possible. Once a transaction has been completed, some planning opportunities may no longer be available.
Several legitimate ways may reduce or defer CGT depending on your circumstances:
- Use Your Annual Exempt Amount: Plan disposals carefully so the available £3,000 allowance is not unnecessarily wasted
- Claim Allowable Losses: Current and qualifying carried-forward capital losses can reduce taxable gains
- Use Available Tax Wrappers: Eligible investments held inside an ISA can grow without Capital Gains Tax
- Claim Relevant Reliefs: Private Residence Relief, Business Asset Disposal Relief and other business reliefs may reduce or defer tax where the qualifying rules are met
Transfers between spouses or civil partners can also form part of legitimate planning because eligible transfers can take place on a no-gain, no-loss basis.
However, the recipient generally takes over the relevant base cost, so the future tax consequences should still be considered.
CGT planning becomes more important where you are disposing of a business, investment property, substantial shareholding or several assets in the same tax year.
Professional tax advice may be worthwhile where the sums are significant or the ownership history is complicated.
Frequently Asked Questions
Do You Pay Capital Gains Tax If Your Gain Is Under £3,000?
Generally, an individual whose total eligible net gains for 2026/27 do not exceed the £3,000 annual exempt amount will have no CGT to pay, although separate reporting rules can apply in certain circumstances.
How Much CGT Would You Pay on a £10,000 Gain?
After the £3,000 annual exempt amount, £7,000 may remain taxable. That would produce £1,260 of CGT if all of it falls within the 18% band or £1,680 if all of it is taxed at 24%.
How Much Capital Gains Tax Does a Higher Rate Taxpayer Pay?
For gains made from 6 April 2026, higher and additional rate taxpayers generally pay 24% on taxable capital gains that do not qualify for a special relief.
Do You Pay Capital Gains Tax When Selling Your Main Home?
Usually not if you qualify for full Private Residence Relief. CGT can arise where part of the property was exclusively used for business, it was partly let or other relief conditions are not satisfied.
Do You Pay Capital Gains Tax on Shares?
You may pay CGT when selling shares held outside an ISA or another exempt arrangement if your taxable gains exceed the available allowance after losses and reliefs.
Do You Pay Capital Gains Tax on Cryptocurrency?
Potentially. Selling crypto, exchanging it for another cryptoasset, spending it or giving it away can count as a disposal for CGT purposes.
How Long Do You Have to Pay Capital Gains Tax on Property?
CGT due on a UK residential property disposal generally has to be reported and paid within 60 days of completion.
Startup mentor & Blogger | Sharing leadership tips for UK business owners
Related Articles in Finance
View All →
If I Take Home £1,600 a Month, What Is My Salary in the UK?
If an employee takes home £1,600 per month in the UK, their estimated gross salary is approximately £21,780 per year. This is equal to about £1,815 per month…
Why the Two Year Accounts Rule is Not Actually a Rule?
Ask most new business owners when they can first apply for a mortgage and the answer comes back the same way every time: two years of accounts, minimum,…

Snap-on Franchise Cost: Fees, Investment and Earnings
The Snap-on franchise cost in the UK is currently quoted at £166,597 to £168,487 for the franchise investment, with Snap-on stating that a new franchisee may need to…