How To Set Up A Limited Company In The UK?

UK Startup Blog Archive
Table of Contents
Setting up a limited company in the UK creates a business that is legally separate from the people who own and manage it.
For many founders, this can provide limited liability, a clearer ownership structure and greater flexibility when bringing shareholders into the business.
The process is relatively straightforward once you have the required information ready.
You need to decide what type of company you are forming, choose directors and owners, identify people with significant control, prepare company details and complete registration with Companies House.
In 2026, online incorporation through Companies House costs £100 and a straightforward application is usually processed within 24 hours.
Is A Limited Company Right For Your Business?
A limited company is a separate legal entity. This means the company can enter contracts, own assets, employ staff and incur debts in its own name rather than in the name of an individual owner.
For a company limited by shares, shareholders’ financial liability is generally limited to the amount they have invested or still owe on their shares.
This separation can make a limited company attractive where a business is growing, taking on commercial risk, bringing in investors or working with larger customers.
However, incorporation also creates additional responsibilities.
Directors must maintain company records, submit required information to Companies House and ensure that accounts and tax obligations are dealt with correctly.
A sole trader generally has fewer administrative responsibilities, so incorporation is not automatically the best choice for every small business.
Your expected profits, risk exposure, ownership plans and long-term goals should all influence the decision. These considerations form part of the wider decisions involved in starting a business in the UK.
What Do You Need Before Setting Up A Limited Company?
Preparing your information before beginning the Companies House application can make registration much easier.
You will normally need:
- Company Name: Choose an acceptable name that is not the same as an existing registered company and does not breach naming restrictions.
- Company Type: Decide whether the business will be limited by shares or limited by guarantee.
- Director Details: Every company needs at least one director.
- Shareholder Or Guarantor Details: Your ownership information depends on the type of company being created.
- PSC Information: Identify anyone who qualifies as a person with significant control.
- Registered Office: Provide an appropriate physical UK address in the jurisdiction where the company is registered.
- Registered Email: Give Companies House an appropriate email address for official communications.
- SIC Code: Choose the code or codes that best describe the company’s activities.
- Company Documents: Prepare the memorandum and articles of association where required.
You should also decide how ownership will be divided before incorporating if there will be more than one shareholder.
Changing the structure later is possible, but agreeing shareholdings and voting rights at the beginning can prevent unnecessary complications.
Should You Set Up A Company Limited By Shares Or Guarantee?
The two main types of private limited company are limited by shares and limited by guarantee.
Most commercial businesses are limited by shares. They are owned by shareholders and can distribute profits to shareholders through dividends.
A company can have only one shareholder, and the same person can also serve as its sole director.
Companies limited by guarantee do not have shareholders or share capital. Instead, they have guarantors who agree to contribute a specified amount if the company cannot meet its debts.
This structure is commonly used by non-profit organisations, membership bodies, associations and some charities.
For most founders creating an ordinary profit-making startup, a company limited by shares is likely to be the more relevant structure.
However, the choice should reflect what the organisation is intended to do and how profits will be used.
How Do You Set Up A Limited Company Step By Step?
The incorporation process involves more than simply entering a business name on Companies House.
Decisions made during registration determine who controls the company, how ownership is structured and what information appears on the public register.
Choose A Company Name
Your company name must comply with Companies House rules.
It cannot normally be identical to another registered company name and restrictions apply to offensive terms, sensitive words and names suggesting a connection with government or public authorities.
It is also sensible to check trade marks before building a brand around the name. Registering a company name with Companies House does not automatically give you trade mark protection.
Checking company name availability at Companies House before submitting the application can reduce the chance of choosing a name that needs to be changed.
Verify Your Identity And Appoint Directors
Every private limited company must have at least one director. A director must normally be at least 16 years old, although they do not have to live in the UK.
A private company does not have to appoint a company secretary.
Identity verification has also become an important part of company formation. Since 18 November 2025, identity verification has been a legal requirement under the new Companies House regime.
When registering a new company, you are asked to provide the Companies House personal code for each director as part of the registration filing. PSCs also have separate identity-verification requirements.
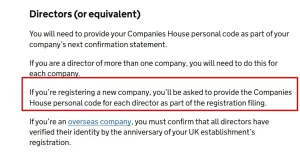
Companies House confirms that each director of a new company must provide their personal code as part of the registration filing.
Choose Shareholders And Identify PSCs
A company limited by shares must have at least one shareholder, and that shareholder can also be a director. If there is one shareholder, they can own 100% of the company.
You also need to identify your people with significant control, commonly called PSCs.
A PSC can include someone who:
- Owns More Than 25% Of The Shares
- Controls More Than 25% Of The Voting Rights
- Can Appoint Or Remove A Majority Of Directors
- Otherwise Exercises Significant Influence Or Control
Companies House requires PSC information so that significant ownership and control of UK companies can be identified.
Set Your Registered Office And SIC Code
You need a registered office address for the company.
It must be a physical UK address in the same jurisdiction where the company is registered and must meet Companies House’s requirements for an appropriate address.
You also need at least one Standard Industrial Classification, or SIC, code. This identifies the nature of the company’s business activities.
Choose the code that most accurately reflects what your company actually does. A company operating across several activities may use more than one SIC code where appropriate.
Prepare Company Documents And Register With Companies House
Companies generally need a memorandum of association and articles of association.
The memorandum records the initial members’ intention to form the company. If you register online, the memorandum is normally generated automatically.
The articles of association contain the rules governing how the company operates.
You can normally use standard model articles or provide suitable bespoke articles where the company’s structure requires something different.
Once the information is ready, you can complete your Companies House application.
Businesses wanting a more detailed look at the filing process can also review how to register a new company with Companies House.
Successful registration produces a certificate of incorporation confirming that the company legally exists and showing its company number and incorporation date.
What Registered Office And Privacy Rules Should You Know?
The address you use during incorporation deserves careful consideration because the registered office becomes publicly available on the Companies House register.
The registered office must be a physical UK address and must be located in the same UK jurisdiction in which the company is registered.
It must also be somewhere company correspondence can reasonably be expected to reach someone acting for the business. A PO Box on its own cannot be used as the registered office.
If you work from home, you can use a home address if it satisfies the requirements, but doing so means that address will normally become public.
Founders concerned about privacy may instead use an appropriate accountant, solicitor or registered-office service with permission.
Companies must also provide a registered email address.
Unlike the registered office, Companies House does not publish that email address on the public register. The business is expected to monitor it because Companies House may use it for official communications.
Directors should also understand that some personal information, including their name and service address, appears publicly on Companies House.
How Much Does It Cost And How Long Does Registration Take?
The amount you pay depends on how you submit the application.
| Registration Method | Companies House Fee | Typical Processing Time |
| Online Registration | £100 | Usually Within 24 Hours |
| Postal Registration | £124 | Around 8 To 10 Days |
The £100 fee applies to the standard Companies House online incorporation service.
Straightforward online applications are usually registered within 24 hours, although applications requiring further checks can take longer.
Postal applications are more expensive and normally take between eight and ten days to process.
Formation agents and professional advisers can also charge their own service fees in addition to Companies House charges.
The cheapest option is therefore not always the only consideration.
Businesses with several shareholders, unusual articles or more complex ownership arrangements may benefit from professional advice before submitting the incorporation.
What Should You Do After Registering Your Limited Company?
Receiving your certificate of incorporation is the beginning of your responsibilities rather than the end of the process.
The certificate confirms the company’s legal existence and contains its registered company number and formation date. You should store it securely with the company’s statutory records.
Companies registered through the online service are normally set up for Corporation Tax at the same time unless they are dormant.
Once your 10-digit Unique Taxpayer Reference arrives, you may need it when adding Corporation Tax services to your business tax account.
Understanding the difference between your company number, UTR, PAYE references and VAT number can prevent problems when completing tax forms.
Each serves a different purpose, which is why keeping your business tax reference numbers organised from the start is useful.
You should also:
- Separate Company Finances: Keep company money separate from personal funds, normally through a dedicated business account.
- Set Up Accounting Records: Record income, expenses, assets and liabilities accurately.
- Consider PAYE: Register where the company will pay employees or directors through payroll.
- Check VAT Requirements: Register if the company meets the applicable VAT registration requirements.
- Review Insurance: Check whether employers’ liability, public liability, professional indemnity or other cover is appropriate for your activities.
Keeping these systems organised from the first transaction makes future accounts and tax reporting considerably easier.
What Filing And Tax Responsibilities Does A Limited Company Have?
Limited companies have ongoing reporting responsibilities to both Companies House and HMRC.
For a typical private limited company, the main deadlines include:
| Requirement | Standard Deadline |
| First Accounts | 21 Months After Incorporation |
| Annual Accounts | 9 Months After The Financial Year Ends |
| Corporation Tax Payment | 9 Months And 1 Day After The Accounting Period Ends |
| Company Tax Return | 12 Months After The Accounting Period Ends |
These deadlines are separate. Paying Corporation Tax does not replace the requirement to submit the Company Tax Return, and filing accounts with Companies House does not automatically mean every HMRC requirement has been completed.
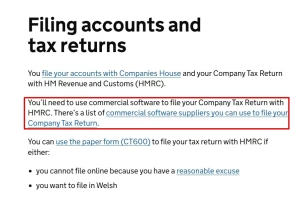
The official GOV.UK table shows the standard deadlines for first accounts, annual accounts, Corporation Tax payments and Company Tax Returns.
You must also file a confirmation statement with Companies House at least once every 12 months.
It confirms that important company information such as the registered office, directors, share capital, shareholders, SIC codes and PSC details is correct.
You can file the statement up to 14 days after the relevant review period ends. In 2026, the standard fee is £50 online or £110 by post.
Failure to file can lead to penalties and, in serious cases, the company being struck off the register.
Directors remain legally responsible for making sure these responsibilities are met even where an accountant, company secretary or other adviser handles the administrative work.
When Should You Move From Sole Trader To Limited Company?
There is no fixed turnover or profit level at which every sole trader should become a limited company.
The decision usually becomes worth reviewing when the business grows, financial risks increase, additional owners are joining or customers and investors expect a formal company structure.
A limited company may become more attractive when you want to:
- Limit Personal Liability: The company is normally responsible for its own liabilities.
- Bring In Co-Owners: Shares provide a structured way to divide ownership.
- Raise Investment: Investors can potentially receive shares in return for capital.
- Build Business Continuity: The company can continue independently of an individual founder.
- Create A Formal Structure: Directors, shareholders and voting rights can be clearly defined.
However, incorporation comes with more administration, public filing requirements and potentially higher accounting costs.
You should not change structure purely because you have heard that limited companies always pay less tax. The most suitable structure depends on your profits, how you take money from the business and your wider circumstances.
If you move from sole trader status to a limited company, remember that the company is a new legal entity.
Existing contracts, assets, bank arrangements, employees and tax registrations may therefore need to be reviewed or transferred rather than assuming everything automatically moves to the company.
Frequently Asked Questions About Setting Up A Limited Company
Can One Person Set Up A Limited Company?
Yes. A private company limited by shares can have one shareholder who owns 100% of the shares and acts as the company’s only director.
Do I Need An Accountant To Set Up A Limited Company?
There is no general requirement to appoint an accountant simply to incorporate a standard limited company.
However, professional advice can be useful where the ownership, tax position, share structure or articles of association are more complicated.
Does A Private Limited Company Need A Company Secretary?
No. A private limited company does not have to appoint a company secretary. Directors remain legally responsible for the company even if a secretary is appointed.
Can I Use My Home Address As My Registered Office?
You can use a home address if it meets Companies House requirements. However, the registered office is published on the public register, so consider the privacy implications before doing so.
How Long Does It Take To Set Up A Limited Company?
A standard Companies House online application is usually processed within 24 hours.
Postal applications generally take around eight to ten days. Complex applications or those requiring additional checks may take longer.
Do I Have To Start Trading Immediately After Incorporation?
No. A company can remain dormant if it has not started trading.
Dormant companies still have Companies House responsibilities, so incorporation should not be treated as a way to avoid future filing requirements.
Expert Blogger | Strategic thinker anticipating future directions for UK business
Related Articles in Business
View All →
Is Specsavers a Franchise? UK Partnership Model, Costs, Ownership and Requirements
Specsavers is not a traditional franchise in the UK. If you want to run a Specsavers business, the route is normally its Joint Venture Partnership model, where local…
Chick-fil-A Franchise Cost in 2026: UK Investment, Fees, Profits and Requirements
The Chick-fil-A franchise cost in the UK is approximately £10,000, making it an unusually accessible entry point into the international fast-food franchise market. In the United States, the…
The Best Digital Marketing Agencies for Enterprise Brands in the UK
When it comes to enterprise-scale marketing campaigns, the toughest challenge is ensuring coordination between the different channel teams. It’s understandable when you consider the complexity, with teams targeting…