Self Employed Carer Hourly Rate UK 2027: How Much Should You Charge?

UK Startup Blog Archive
Table of Contents
The self employed carer hourly rate in the UK typically falls between £18 and £28, based on published 2026 private-care pricing guides. However, some carers charge more for specialist support, overnight shifts, difficult-to-cover locations or additional responsibilities.
For 2027, independent carers should review their rates against rising employment costs, local demand, travel expenses and the time they spend working without being paid.
From April 2027, the National Living Wage for employees aged 21 and over will increase to £13.21 per hour, representing a 3.9% rise from £12.71 in 2026.
Although genuinely self-employed carers are not automatically covered by minimum wage legislation, the change provides an important benchmark for evaluating whether independent work remains financially worthwhile.
We analysed published carer rate cards, homecare industry research, tax rules and the costs involved in providing private care.
Our findings suggest that the most important figure is not simply what a family pays per hour. It is how much the carer retains after business expenses, unpaid working time and tax.
This article explains what independent carers can reasonably charge, how to calculate annual earnings, what changes in 2027 and how to establish a sustainable private-care business.
What Is the Average Self Employed Carer Hourly Rate in the UK in 2027?
An independent carer providing standard domiciliary or personal care can use £20–£28 per hour as an initial 2027 pricing benchmark, provided that the figure is checked against actual local demand and individual business costs.
This is a recommended planning range, not a measured UK-wide average for 2027. Published 2026 benchmarks generally place private visiting care between £18 and £25 per hour, with some providers advertising higher rates.
The following comparison separates published 2026 prices from our 2027 planning estimates.
| Type of care | Published 2026 pricing benchmarks | Indicative 2027 pricing approach |
| Companionship | £15–£20/hour | Consider £17–£22/hour |
| Standard personal care | £18–£25/hour | Consider £20–£28/hour |
| Experienced or specialist care | Varies by skill and responsibility | Cost individual work at approximately £24–£35+/hour |
| Sleep-in overnight care | £160–£190/night on a leading introductory platform | Review fixed-night fees against duties and interruptions |
| Waking-night care | £165–£250/night on the same platform | Price according to all hours actively worked |
| Live-in care | £1,050–£1,400/week on the same platform | Recalculate according to duties, rotation and rest arrangements |
The 2027 figures are editorial budgeting examples rather than official tariffs or independently measured market averages.
Rates for specialist services must reflect the carer’s competence, authorised responsibilities and any applicable regulatory requirements.
A carer working independently in a rural area may need to charge more than a carer serving several clients within walking distance.
Likewise, one providing demanding personal care may need a higher charge than someone primarily offering companionship.
Families comparing private care with a regulated agency should remember that the services and responsibilities may be different.
How Will the 2027 Minimum Wage Increase Affect Self-Employed Carers?
The government has confirmed that the National Living Wage will rise from £12.71 to £13.21 per hour on 1 April 2027 for eligible workers aged 21 and over.
The increase is approximately 3.9%, following the 4.1% uplift introduced in April 2026.
| Period | National Living Wage (21+) | Change |
| April 2025 | £12.21 | — |
| April 2026 | £12.71 | +4.1% |
| April 2027 | £13.21 | +3.9% |
These rates apply to eligible employees and workers, not automatically to genuinely self-employed businesses.
Nevertheless, they are useful when comparing independent care work with an employed position offering holiday pay, qualifying pension contributions and other statutory protections.
For example, a self-employed carer currently charging £24 per hour could apply a 3.9% pricing review:
£24 × 1.039 = £24.94 per hour.
Rounding the new rate to £25 would maintain approximately the same uplift as the announced minimum wage increase, although it would not necessarily offset every business expense.
Our analysis suggests that carers should avoid increasing prices solely because the minimum wage has changed.
A comprehensive annual pricing review should also consider fuel, insurance, client demand, cancellations and non-billable time.
For a better understanding of how employment costs work, see our explanation of calculating hourly rates from annual salaries.
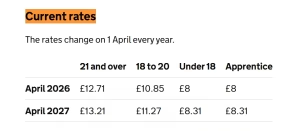
UK National Living Wage rates for April 2026 and April 2027, showing the increase from £12.71 to £13.21 for workers aged 21 and over.
How Much Does a Self-Employed Carer Actually Earn After Expenses?
A carer charging £25 per hour does not automatically earn £25 in personal income.
Independent carers normally pay for various operating expenses themselves. Depending on the arrangement, these can include:
- Professional indemnity or public liability insurance.
- Business travel and parking.
- Training, appropriate checks and renewals.
- Accounting software and professional fees.
- Marketing and client acquisition.
- Unpaid cancellations and gaps between bookings.
- Holiday provision, retirement savings and emergency reserves.
Some carers also pay commission to introductory platforms.
James Bowdler, founder of PrimeCarers, expressed this distinction in his September 2026 pricing guidance:
“Your rate has to pay for more than the hour in front of you.”
His observation highlights why advertised rates cannot be compared directly with an employee’s hourly wage.
Example: A Carer Charging £25 Per Hour
Consider an independent carer providing 24 billable hours per week for 46 weeks a year.
| Financial calculation | Annual amount |
| Hourly charge | £25 |
| Weekly billable hours | 24 |
| Working weeks | 46 |
| Total billable hours | 1,104 |
| Annual turnover | £27,600 |
| Illustrative business expenses | £3,500 |
| Profit before tax | £24,100 |
| Estimated Income Tax | £2,306 |
| Estimated Class 4 National Insurance | £691.80 |
| Estimated income after tax and NI | £21,102.20 |
This represents approximately £1,758.52 per calendar month after the modelled expenses, Income Tax and Class 4 National Insurance.
The calculation uses the 2026/27 England, Wales and Northern Ireland basic-rate Income Tax framework, with a full Personal Allowance and no other income, adjustments or student loan repayments. Scottish taxpayers may have different Income Tax liabilities.
The example does not include personal pension contributions or unexpected additional costs. It is an illustration, not a personalised tax estimate.
The important distinction is that a £25 customer-facing hourly rate produces approximately £19.11 of annual after-tax income per billed hour in this scenario.
Anyone reviewing their business finances should calculate the difference between revenue, taxable profit and personal income rather than treating all customer payments as earnings.
How Can You Calculate the Right Hourly Rate for Your Care Business?
The most reliable way to set an independent carer’s hourly rate is to work backwards from the annual profit required.
Instead of guessing a price based on competing advertisements, start with a straightforward formula:
Hourly rate = (Target annual profit + annual business expenses) ÷ annual billable hours
Suppose a self-employed carer wants:
- £30,000 annual profit before personal taxes.
- £4,000 for business expenses.
- 27 billable hours per week.
- 46 working weeks per year.
Annual billable hours:
27 × 46 = 1,242 hours.
Required annual revenue:
£30,000 + £4,000 = £34,000.
Required hourly rate:
£34,000 ÷ 1,242 = £27.38.
This carer would therefore need to charge approximately £28 per hour to achieve the proposed profit target, assuming every planned billable hour is actually paid.
Our analysis also shows how dramatically changes in the hourly rate can influence business sustainability.
Our Pricing Sustainability Assessment
For the following illustration, we assumed 1,104 billable hours per year, £3,500 in operating expenses and a target of £24,000 annual profit before tax.
| Hourly charge | Annual turnover | Profit before tax | Profit target achieved |
| £18 | £19,872 | £16,372 | 68% |
| £20 | £22,080 | £18,580 | 77% |
| £22 | £24,288 | £20,788 | 87% |
| £25 | £27,600 | £24,100 | 100% |
| £28 | £30,912 | £27,412 | 114% |
These percentages are calculated from the stated example rather than customer surveys or industry ratings.
A £28 rate may look only slightly higher than £22, but across the same working schedule it produces £6,624 more annual turnover.
Carers can adapt the same approach using our hourly rate calculation guide to establish a price that reflects their financial needs.
Why Do Private Carer Rates Vary Across Different UK Regions?
Geography influences the economics of self-employed care, but higher charges in London are not guaranteed.
Published platform transaction data from the 12 months to September 2026 shows meaningful variation across regions.
The following figures represent the average amount families paid for completed bookings on one introductory care platform, including its charges. They should not be interpreted as universal regional market averages.
| Region | Average family-paid hourly rate | Carer retained after platform fee |
| London | £20.97 | £17.07 |
| South East England | £20.84 | £16.86 |
| North West England | £19.56 | £16.28 |
| East Midlands | £24.06 | £19.40 |
| Scotland | £18.18 | £15.12 |
| Wales | £24.87 | £20.06 |
Wales had a relatively small transaction sample, while the East Midlands figure was based on fewer completed hours than London. These differences limit broad regional conclusions.
Across the platform’s reported UK bookings, families paid approximately £21.08 per hour, and carers retained approximately £17.14 before their own business expenses and tax.
For a self-employed carer, postcode is therefore only one part of pricing.
A more useful local comparison considers the travel distance between appointments, the number of available carers, required qualifications and whether families are seeking short visits or longer, recurring arrangements.
Our preferred approach is to compare at least three genuinely comparable local care arrangements before confirming a rate. That is a suggested research method, not a claimed survey of care workers.
How Much Should Carers Charge for Dementia, Overnight and Live-In Care?
Care pricing becomes more complicated when appointments involve specialist responsibilities or substantial periods of availability.
An independent carer should only agree to work they are trained, competent, insured and legally permitted to perform.
Dementia and Complex Personal Care
Supporting someone living with dementia can involve communication difficulties, distress, behavioural changes, supervision and additional safety considerations.
Carers with appropriate training and experience may reasonably charge a premium for more demanding assignments.
However, there is no universal statutory dementia-care supplement. A proposed specialist rate should reflect the individual person’s support needs rather than the diagnosis alone.
A carer should not accept clinical tasks simply because a higher fee is available.
Waking-Night Care
A waking-night arrangement requires the carer to remain awake and available throughout the agreed shift.
For example, ten hours of waking-night care at £24 per hour would cost £240.
The contract should clarify whether the carer must remain continuously awake, what duties are expected and how breaks are managed.
Sleep-In Care
A sleeping-night arrangement normally involves the carer staying overnight and responding when necessary.
Unlike waking-night care, this is usually priced as a fixed booking.
The agreement should define anticipated interruptions and what happens if the person’s needs change so significantly that the arrangement effectively becomes waking-night care.
Live-In Care
Live-in care is commonly priced weekly rather than purely by the hour.
The weekly charge must account for active duties, time off, overnight expectations, handovers and arrangements for relief cover.
A live-in booking does not automatically mean that one carer can provide uninterrupted active care 24 hours a day.
The correct care plan must allow safe working arrangements and appropriate rest.
Is Working as a Self-Employed Carer Better Than Working Through a Care Agency?
Working independently may give carers greater control over their fees, working patterns and client relationships. However, it also transfers more financial and administrative responsibility to the individual.
| Comparison | Independent carer | Employed agency carer |
| Hourly payment | Negotiated or self-set | Contractual wage |
| Paid annual leave | Must fund personally | Statutory entitlement |
| Insurance arrangements | Must arrange appropriate cover | Normally managed by employer for employed duties |
| Income Tax | Generally through Self Assessment | Normally PAYE |
| Pension | Personal arrangements | Workplace pension where eligible |
| Finding clients | Carer’s responsibility or introductory platform | Usually agency responsibility |
| Cancellation risk | Contract-dependent | Depends on employment terms |
| Administrative work | Carer handles or outsources | Usually agency-managed |
A higher hourly invoice does not necessarily mean a higher standard of living.
In our financial assessment, the most important advantage of independent care is the potential to build a reliable client base with appropriately priced recurring work.
A carer regularly filling six-hour shifts may earn more efficiently than one travelling between several distant one-hour appointments.
Similarly, introductory platform fees require careful evaluation. If a platform deducts 20% from a £25 booking, the carer receives £20 before other operating expenses and taxes.
Carers planning to expand beyond individual work can investigate how to start a care agency, although operating a regulated business may involve significantly different responsibilities.
What Do Travel Time and Short Care Visits Really Cost?
Travel can substantially reduce the effective hourly earnings of a domiciliary carer.
Consider a one-hour appointment charged at £25.
If the journey and related administration take another hour, the carer has committed two hours to earning £25.
That produces an effective gross return of £12.50 per hour of time committed, before fuel, insurance and tax.
We therefore suggest considering minimum booking periods or transparent travel arrangements when short, isolated visits are commercially unsustainable.
For example, two consecutive hours at £25 produce £50 in revenue. If the total travel and administration time remains one hour, the effective rate becomes approximately £16.67 across three hours committed.
This illustrates why the location and scheduling of visits can matter as much as the headline fee.
A significant 2026 development is the change to HMRC’s simplified vehicle expense rates.
From the 2026/27 tax year, eligible self-employed people using the simplified mileage method can calculate car or van expenses at 55p per business mile for the first 10,000 miles, compared with 45p previously. The rate for subsequent miles remains 25p.
This is a tax-deduction calculation, not a requirement for families to pay 55p per mile.
Carers must retain appropriate records and should not claim simplified mileage expenses alongside incompatible actual vehicle-cost claims.
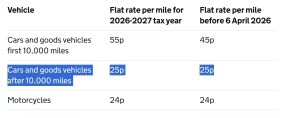
HMRC simplified vehicle expense rates for 2026/27, showing the increase to 55p for the first 10,000 qualifying business miles.
The financial importance of travel is supported by care-sector evidence. In July 2026, Homecare Association research involving 202 providers found that 80% of care workers used their own vehicles and 59% of providers reimbursed mileage at 40p or less.
Dr Jane Townson OBE, Chief Executive of the Homecare Association, raised concerns about the financial pressure created by rising fuel costs and inadequate care funding.
The distinction matters for independent carers: a travel expense allowance can reduce taxable profit, but it does not directly reimburse the money spent at the petrol station.
How Do Self-Employed Carers Pay Tax and National Insurance in 2027?
Independent carers operating as sole traders generally pay tax on their taxable business profits, not their gross customer receipts.
Taxable profit is normally calculated by subtracting allowable business expenses from business income, subject to the relevant tax rules.
For the 2026/27 tax year, the standard Personal Allowance is £12,570. The main basic Income Tax rate for England, Wales and Northern Ireland is 20%, while Scotland uses different rates and bands.
Class 4 National Insurance is charged at:
| Annual taxable self-employed profits | Class 4 NI rate |
| Up to £12,570 | 0% |
| £12,570–£50,270 | 6% on the amount in the band |
| Above £50,270 | 2% on the amount above that threshold |
The 2027/28 Budget figures retain these Class 4 rates and thresholds.
For 2026/27, Class 2 contributions are generally treated as paid where profits reach £7,105. Carers below this level may be able to make voluntary contributions, depending on their circumstances.
Registering and Keeping Financial Records
A new sole trader normally needs to register with HMRC when their circumstances require Self Assessment, including where gross trading income exceeds the relevant £1,000 trading allowance threshold.
Carers unfamiliar with the process can review how to apply for a UTR number and establish a reliable bookkeeping system from the beginning.
A dedicated account can make it easier to track client receipts and operating expenses. Our comparison of business current accounts explains the practical considerations.
It is also sensible to review accountancy costs before deciding whether to manage annual tax returns independently.
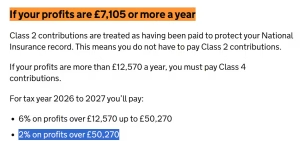
HMRC’s Class 4 National Insurance rates and profit thresholds for the 2026/27 tax year.
What Changes Under Making Tax Digital?
An important 2027 consideration is the expansion of Making Tax Digital for Income Tax.
From 6 April 2027, qualifying sole traders and landlords with combined gross self-employment and property income above £30,000 for the 2025/26 tax year generally enter the new system, subject to exemptions and eligibility rules.
The qualifying income figure is based on gross income rather than profit after expenses.
Affected carers must use compatible software, maintain digital records and send quarterly updates to HMRC.
The phased timetable also includes an April 2028 entry point for qualifying income above £20,000 in the 2026/27 tax year.
Anyone approaching the relevant thresholds should understand Making Tax Digital requirements before choosing an accounting solution.
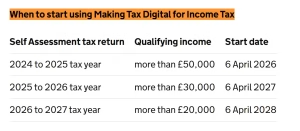
HMRC Making Tax Digital implementation timetable, including the April 2027 threshold of more than £30,000 qualifying income.
Do Self-Employed Carers Need CQC Registration or an Employment Contract?
The regulatory position depends on the work being provided, the legal relationship and who directs the care.
In England, certain individual care workers who provide personal care directly under the control of the person receiving care, or an eligible related third party, may fall within an exemption from Care Quality Commission registration.
However, that exemption is not automatic simply because someone describes themselves as self-employed.
An individual or organisation taking an ongoing role in arranging, directing or managing regulated personal care may have different registration obligations.
The Care Quality Commission’s guidance on individual care workers explains the circumstances in which registration requirements and exemptions apply.
Regulatory arrangements also differ across Scotland, Wales and Northern Ireland.
Employment status is a separate question. A carer may be considered an employee or worker for relevant legal or tax purposes even where invoices are issued or a contract calls the arrangement self-employed.
For that reason, both families and carers should check the actual working relationship rather than relying exclusively on contractual labels.
Where a family directly employs a personal assistant, it may have obligations involving payroll, employment contracts, minimum wage, insurance and pensions.
Our articles on employment contracts and managing payroll explain these wider administrative responsibilities.
CQC guidance explaining when individual care workers and introductory agencies may be exempt from personal care registration.
What Should Be Included in a Self-Employed Carer’s Price Agreement?
A properly documented care arrangement protects both the individual providing care and the person purchasing it.
The agreement should clearly explain:
- The precise care tasks and boundaries of responsibility.
- The agreed hourly or fixed booking charge.
- Minimum visit duration and payment terms.
- Travel charges and expenses where applicable.
- Weekend, bank holiday and emergency arrangements.
- Cancellation and notice periods.
- Arrangements for sickness, annual leave and replacement cover.
- Handling of personal information and confidential care records.
- Insurance, safeguarding, reporting and complaint arrangements.
Any pricing changes should be agreed according to the contract rather than imposed retrospectively.
A useful example would be a carer charging £25 per hour for three daily visits lasting two hours each.
The daily price would be £150, excluding any agreed additional charges.
If care were required seven days a week at the same rate, the weekly cost would be £1,050.
Families should receive a clear statement of what that fee includes and when payment is due.
For business owners, regular review of unpaid invoices, unexpected expenses and available cash is particularly important.
A structured financial health check can reveal problems that high advertised hourly earnings might otherwise conceal.
How Can Self-Employed Carers Increase Their Earnings in 2027?
Increasing an hourly rate is not the only way to improve earnings. Better scheduling, appropriate specialisation and lower operating costs can make a significant difference.
We recommend considering the following practical improvements:
- Prioritise recurring bookings: Regular appointments can reduce the time and expense involved in finding replacement clients.
- Reduce unnecessary travel: Group geographically close visits wherever practical without compromising care needs.
- Develop relevant skills: Additional competence in dementia support, mobility assistance or other appropriate areas may improve access to more specialised work.
- Set sustainable booking terms: Agree minimum visits and cancellation rules that balance client needs with commercial sustainability.
- Monitor platform deductions: Compare the value of introductions, administration and payment processing with the fees retained by each provider.
- Review prices annually: Reassess expenses, local market demand and minimum wage developments rather than leaving rates unchanged indefinitely.
- Maintain professional standards: Appropriate training, dependable communication, insurance and documented care arrangements can strengthen confidence among potential clients.
The objective should be sustainable income and continuity of care rather than maximising charges at the expense of affordability or service quality.
Is Becoming a Self-Employed Carer Worth It in 2027?
Self-employment can be financially attractive for an experienced care worker with a reliable client base, appropriate skills and the ability to manage business responsibilities.
The opportunity becomes less attractive when most appointments are short, travel is substantial, bookings are irregular or commission reduces an already low hourly charge.
The Homecare Association’s October 2026 research illustrates the wider pricing pressures facing the sector.
Its analysis of 176 regular homecare contracts across 107 English local authorities found an average publicly commissioned fee of £25.37 per hour, compared with a calculated minimum sustainable price of £34.42 for a regulated homecare provider.
It also found that 61% of the contracts with available figures were below £26.17 per hour, the estimated direct cost of employing a care worker at the statutory minimum wage before other operating expenses.
Those provider-level figures are not recommended hourly wages for self-employed carers. They illustrate the broader cost of delivering regulated care, including employment obligations, travel, management and service overheads.
Jane Townson OBE highlighted the urgency of this funding challenge in her response to the October 2026 Budget:
“The sector cannot wait for long-term reform: homecare needs sustainable funding now.”
For independent carers, the commercial lesson is similar: setting an hourly rate without accounting for the cost of providing the service can undermine long-term viability.
Conclusion
The self employed carer hourly rate in the UK depends on qualifications, care requirements, location, working arrangements and business expenses.
Published 2026 rates provide a useful foundation for 2027 planning, but no single hourly figure will be commercially sustainable for every independent carer.
Our analysis suggests that carers should calculate rates from their required annual profit, realistic billable hours and full operating costs rather than copying a competitor’s advertised fee.
The April 2027 minimum wage increase, updated mileage rules and Making Tax Digital requirements make financial planning particularly important.
A sustainable rate must support both dependable care and the carer’s long-term financial security.
Frequently Asked Questions
What is a reasonable hourly rate for a self-employed carer in 2027?
A starting pricing benchmark is approximately £20–£28 per hour for standard independent care, but this is a planning range rather than an official average. The appropriate charge depends on duties, experience, local demand, expenses and the carer’s actual billable hours.
Can a self-employed carer charge £30 per hour?
Yes. A genuinely self-employed carer may negotiate a £30 hourly rate where appropriate. However, the price should reflect the work involved, local demand and the carer’s competence rather than being treated as a standard national tariff.
How much do private carers earn per month?
A carer charging £25 per hour for 24 weekly billable hours across 46 working weeks generates £27,600 in annual turnover.
In our illustrated tax and expense model, this produces approximately £1,759 monthly after business expenses, Income Tax and Class 4 National Insurance.
Do self-employed carers receive holiday pay?
Genuinely self-employed carers do not automatically receive statutory paid annual leave from customers. They should account for unpaid leave when setting rates. Different rights may apply if the actual working relationship creates employee or worker status.
Can carers charge double on bank holidays?
They can negotiate enhanced rates, but double payment is not universally guaranteed. Any bank holiday supplement should be agreed in the contract before the work takes place.
Do self-employed carers need insurance?
Carers should arrange insurance suitable for their activities and contractual obligations, often including public liability or professional cover. The appropriate policy depends on the work and legal arrangements.
Is £15 per hour enough for a self-employed carer?
It may be difficult to sustain once unpaid travel, leave, cancellations, insurance and taxes are considered.
However, the answer depends on billable hours, business expenses and the nature of the work. If the person is legally an employee or worker, applicable minimum wage protections must also be respected.
Blogger | Business Writer | Sharing startup advice on UK business blogs
Related Articles in Finance
View All →
If I Take Home £1,600 a Month, What Is My Salary in the UK?
If an employee takes home £1,600 per month in the UK, their estimated gross salary is approximately £21,780 per year. This is equal to about £1,815 per month…
Why the Two Year Accounts Rule is Not Actually a Rule?
Ask most new business owners when they can first apply for a mortgage and the answer comes back the same way every time: two years of accounts, minimum,…

Snap-on Franchise Cost: Fees, Investment and Earnings
The Snap-on franchise cost in the UK is currently quoted at £166,597 to £168,487 for the franchise investment, with Snap-on stating that a new franchisee may need to…